REAMER RESEARCH · PYTHON AND C++ BACKTESTING AND LIVE TRADING ENGINE · $20/MONTH
Backtest in Python or C++. Inspect every trade. Send the same orders live.
A deterministic backtesting and live trading engine you install with pip or include as one header. Strategies are plain functions or classes, and every order fills tick by tick on a seeded path inside each bar. When a run ends you get a JSON report and a visual trade diagnostics tool that charts each trade on its own bars, beside every value your strategy printed.
Linux x86-64 · macOS on Apple silicon · Windows through WSL2 · Python 3.9+ · C++20
Three steps to a first run
The kit is a free download that runs in Evaluation Mode: one ticker per backtest over at most 30 days or 50,000 bars, no live trading. A licence removes every limit. Example strategies and data-loading scripts are on GitHub, with the release page and the MCP server for Claude and Cursor.
01 · INSTALL
pip install python/reamer_research-4.11.3-*.whl
C++: add
include/reamer_research.hppwith CMakefind_package, pkg-config or by hand.02 · WRITE A FUNCTION
It receives a window of bars and returns an order, or nothing. Brackets attach in the same call.
return rr.buy_market(10, take_profit=tp, stop_loss=sl)
03 · RUN AND INSPECT
rr.backtest(on_bar, "AAPL.csv", open_viewer=True)
Prints the summary, writes the JSON report and opens the visual trade diagnostics tool. On a headless machine it prints the path to its page.
THE WHOLE QUICKSTART
ATR band reversion with a bracket on every entry
Buy when price closes two ATRs under its 20-bar mean, sell two ATRs over it. Take profit at the mean, stop two ATRs past entry. The same strategy in both languages.
TRADE DIAGNOSTICS
Visual trade diagnostics, the moment a run ends
The run above on 8,142 AAPL 1-minute bars from March 2024: 452 trades. Trade 7, a short, exits at its take profit.
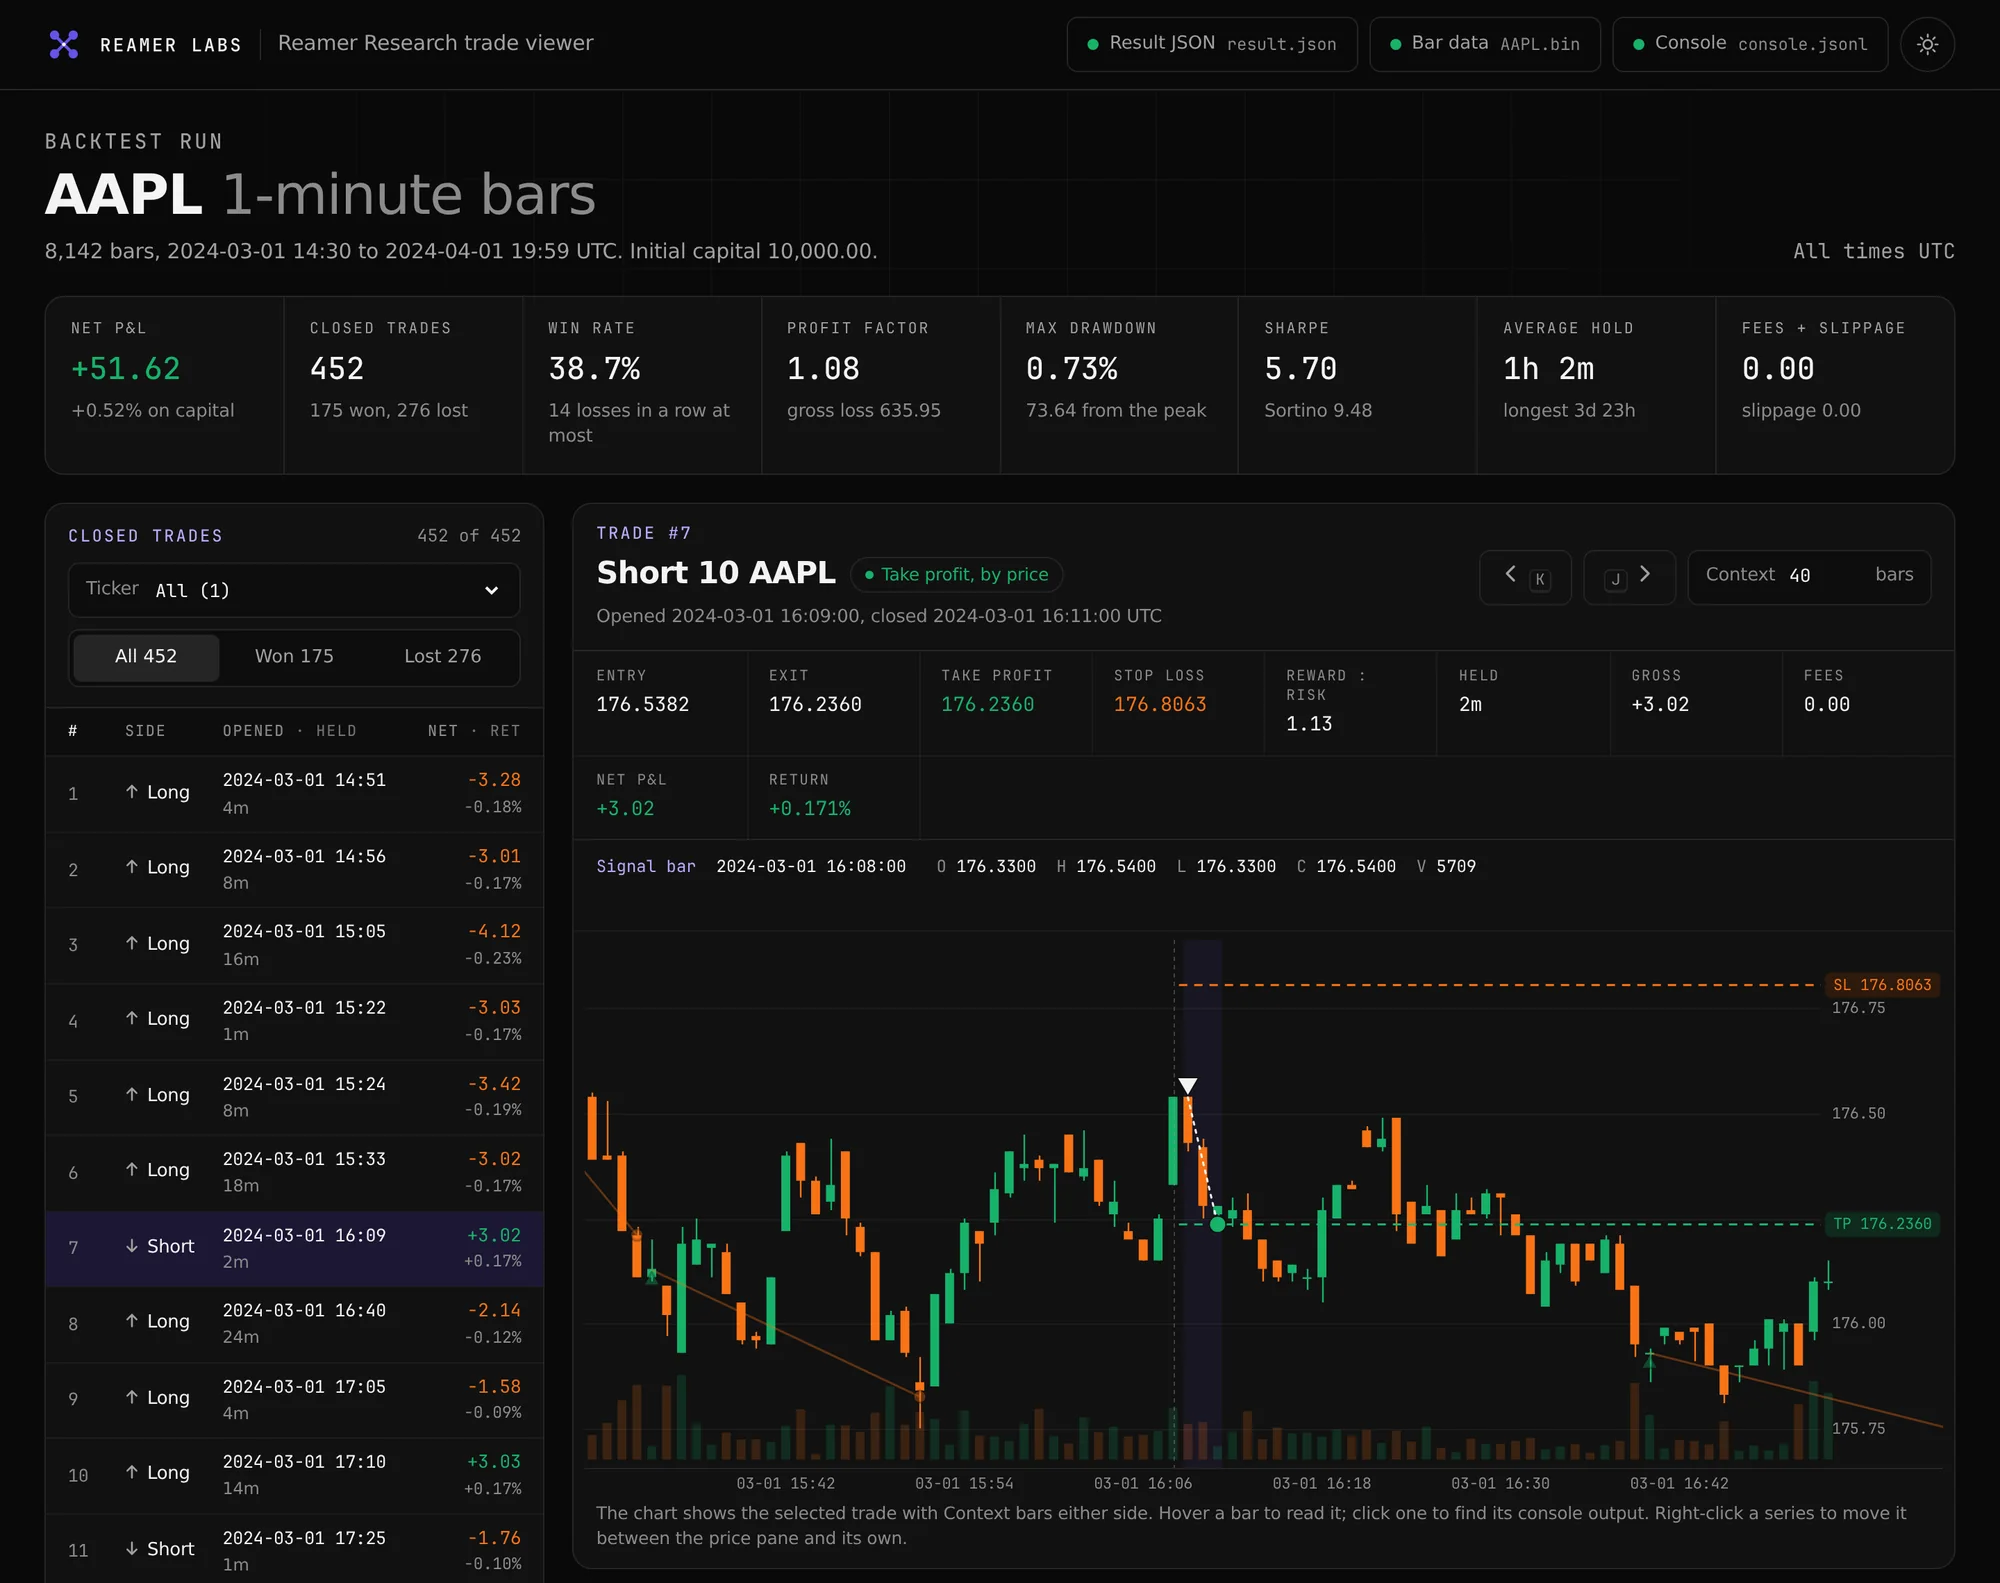
Summary row
Net P&L, trades, win rate, profit factor, max drawdown, Sharpe and fees.
Trade chart
A fixed window of bars around the trade, with entry, exit, take profit and stop loss.
Printed values
Whatever the strategy printed on a bar, shown beside that bar.
Trade table
Every closed trade, any ticker. Sort by P&L to find the worst one.
One HTML file. No network, no install, nothing leaves the browser. Light and dark themes.
EVERYTHING IN THE KIT
Reamer Research features
| AREA | FEATURE | DETAIL |
|---|---|---|
| Languages | Python package | A pip-installable wheel with the engine inside. Python 3.9 or later. |
| Languages | One C++20 header | Pass a lambda. CMake find_package, pkg-config or by hand. |
| Languages | Stable C ABI, version 8 | Rust, Go, Julia, C# or any language that can call C. Backtests, results and the live relay are all in it. Code built against 4.5.0 or later runs as it is. |
| Data | Any input format | CSVs, pandas DataFrames, numpy arrays or memory-mapped files. |
| Data | Bars of any type | Time, tick, volume, dollar, imbalance or your own rule. Each bar's trade count can drive its fills. |
| Data | Multi-ticker, one clock | Tickers need not share timestamps. The strategy sees which have a new bar. |
| Data | Outside data | Any series in your format, visible only from its own timestamp. |
| Data | Any data vendor | One call to the Alpaca or Databento fetchers with your own key, or bars from any source as arrays. Switch vendors any time. |
| Execution | Tick-level fills from bars | Each bar is replayed as a seeded tick path from open through high and low to close, one tick per second or per trade, with bid, ask, spread and slippage on every tick. |
| Execution | Market, limit, stop, brackets | Every order fills on that tick path under the public execution spec, including a stop and a target inside one bar. |
| Execution | Trading costs per ticker | Spread, slippage, commission, swap and margin. |
| Results | Visual trade diagnostics | Every closed trade on its own bars, beside every value your strategy printed, with its console lines and a Monte Carlo simulation. Offline HTML. |
| Results | JSON report | 31 metrics, every trade and every order. |
| Results | Monte Carlo | Seeded resampling of a finished run, from Python or C++. |
| Results | Byte-identical runs | Same seed, same SHA-256 on the report. |
| Live | Any broker, on your terms | The relay sends your strategy's orders to the open-source receiver. Swap its three paper-broker methods for your broker's API calls. |
| Starting points | Templates and examples | 6 templates and 22 examples, in source you can modify. |
| Starting points | Docs for AI agents | Kit docs an AI coding agent can integrate from alone. |
UNDER THE HOOD
Built on a stable C ABI. Any language, live trading included.
The Python package and the C++ header are thin layers over a versioned C interface. Rust, Go, Julia, C# or any language that can call C can wrap it the same way: backtests, the JSON result and the relay that sends orders live are all calls in that interface. Languages →
Measured, with the raw data published
15.8 s
50M bars and 990,000 bracket orders, release 4.6.0.
20 / 20
Runs with one identical SHA-256.
3.38 s
500,000 bars from Python, 0.36 s from C++, release 4.6.0.
14 lines
The full Python quickstart above, bracket included.
$20 / month
Billed monthly, cancel any time. Card checkout, then the licence key and kit by email within minutes. Updates download from your account while you subscribe. Email support from the maintainer.
Every subscription includes
- The engine, the Python package and the C++ header
- The visual trade diagnostics tool
- 6 templates, 22 examples and the data fetchers
- Live and paper trading through the relay
- Every release while you subscribe
Common questions
Do I need Reamer Server to trade live?
No. Live and paper trading are included in the subscription. The relay sends orders to your broker through a receiver over the published protocol, and a working receiver ships in the kit, from Python and C++, and is open source in the examples repository.
Does a backtest give the same result twice?
Yes. A fixed seed gives a byte-identical report.
How does it fill orders from bar data?
On a seeded tick path generated inside each bar, so stops, limits and targets fill where price went within the bar.
Can it test tick, volume or dollar bars?
Yes. You build the bars; the engine treats every type the same way.
What does the trade diagnostics tool need?
A browser. It is one HTML file and makes no network requests.
How fast is it from Python?
500,000 bars in 3.38 s in a published benchmark of release 4.6.0; 0.36 s from C++. The runners for all four engines are on GitHub.
Can Claude or Cursor run backtests with it?
Yes. The Reamer Research MCP server lets Claude Code, Claude Desktop, Cursor and other MCP clients write a strategy, backtest it, read every trade and open visual trade diagnostics on your machine.
Can I use it from Rust, Go or another language?
Yes. Wrap its stable C ABI. Backtesting and live trading through the relay are both in the interface.